The Oklahoma Appraisal Clause: What It Says and How to Use It
A plain guide to the appraisal paragraph in Oklahoma property policies, from the trigger language to the award.
Read the guide
Your insurer accepted the claim, but the check won’t rebuild what the storm took. Oklahoma Insurance Appraiser prepares an independent, line-by-line valuation and carries it through the appraisal process written into your policy.
A few details and we’ll call you back within one business day.
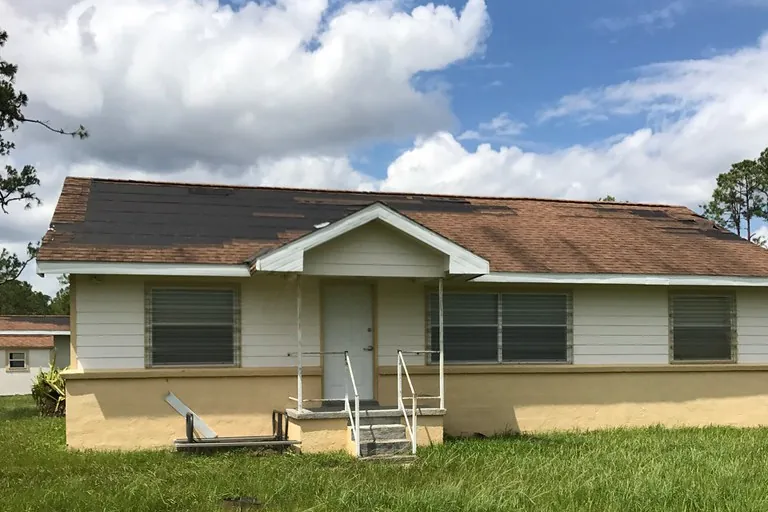
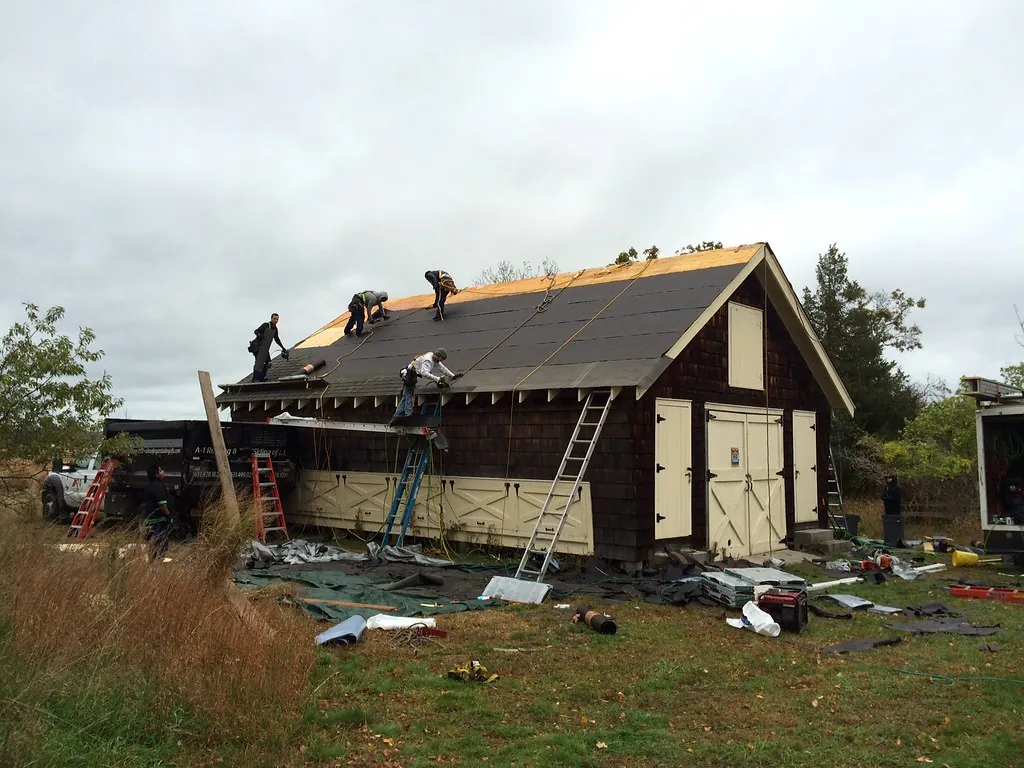
Most underpaid Oklahoma claims aren’t denied. They’re short: a roof measured a few squares low, Class 4 shingles priced as builder-grade, gutters and screens left off, interior water damage that “wasn’t visible yet.” An Oklahoma Insurance Appraiser closes that gap with evidence instead of argument.
Representation when appraisal has been demanded, a second opinion before it is, and the storm and property losses Oklahoma sees most. Pick the closest match — we’ll sort out the details on the call.
 Appraisal RepresentationWe act as the appraiser you name when an Oklahoma claim goes to appraisal over the dollar amount of a covered loss.
 Homeowners Claim AppraisalAppraisal for single-family homes, duplexes and rural properties when the carrier’s estimate leaves out real damage.
 Commercial & HOA AppraisalAppraisal for retail centers, apartments, churches, HOAs and warehouses with large roofs and multi-building claims.
 Carrier Estimate ReviewA line-by-line insurance estimate review that shows what the carrier left out before you decide whether to invoke appraisal.
 Appraisal Umpire ServicesA neutral insurance appraisal umpire for Oklahoma panels when the two appraisers cannot agree on the amount of loss.
 Hail & Roof Damage AppraisalA hail damage appraiser for roofs, siding, gutters and windows when the carrier calls real damage cosmetic or minor.
 Tornado & Wind AppraisalAppraisal for tornado and straight-line wind losses, from lifted shingles to structural damage and total rebuilds.
 Ice Storm & Tree DamageAppraisal for ice storm claims, including falling trees and limbs, roof and gutter damage, ice dams and freeze leaks.
 Water & Pipe Leak AppraisalAppraisal for burst pipes, slab leaks, water heater failures and storm leaks when drying and repair scopes fall short.
 Fire & Smoke Loss AppraisalFire damage appraisal covering structure, smoke and soot cleanup, contents and rebuild costs after house or building fires.
 Wildfire & Grassfire AppraisalAppraisal for wildfire and grassfire losses to homes, barns, fences and outbuildings across Oklahoma’s prairie and plains.
 Earthquake Crack AppraisalAppraisal for covered earthquake damage claims under an endorsement, including cracked brick, foundations and drywall.
The appraisal clause turns an open-ended disagreement into a defined process with a binding result. Here’s how an Oklahoma Insurance Appraiser file moves from the first call to payment.
We read your policy, the carrier’s estimate and your photos, then tell you honestly whether appraisal fits.
Our own inspection and measurements, priced line by line for your part of Oklahoma.
Appraisal is requested in writing and Oklahoma Insurance Appraiser is named as your appraiser.
We work through the differences item by item with the carrier’s appraiser.
Anything left goes to a neutral umpire; two signatures set the amount of loss.
Hail in the metro, ice in Green Country, grass fires on the High Plains, wind off the Wichita Mountains. An Oklahoma Insurance Appraiser has to know how each region’s weather shows up on a roof — and in an estimate.
Seven calculators and planners, free and private. Start with the two-number check on the right: if the gap is large, a conversation makes sense; if it’s small, a documented supplement may close it faster.
Browse all seven tools Calculator
Size the dispute, test where an award might land and subtract flat, percentage or hourly appraisal fees.
Open the calculator → Calculator
List damaged items to estimate the first ACV check, recoverable holdback and total — with a labor depreciation toggle.
Open the calculator → Calculator
Turn a footprint into true roof squares with pitch, waste and drip edge — then compare with the carrier’s diagram.
Open the calculator →CalculatorConvert a 1%, 2% or 5% wind/hail deductible into dollars and see what a storm claim would actually pay.
Open the calculator →PlannerMap notice, proof of loss, appraisal decision, holdback and suit dates from your date of loss — then export them.
Open the planner →ChecklistTen yes/no questions grade your claim file and build a to-do list before you demand appraisal.
Open the checklist → Calculator
See how an age-based roof payment schedule and a percentage deductible shrink a hail claim on an older roof.
Open the calculator →Every big event leaves a pattern in how claims get scoped, priced and disputed. An Oklahoma Insurance Appraiser carries those lessons into every file.
A violent tornado tore through communities southwest and south of Oklahoma City, reshaping how the state thinks about wind-resistant building and safe rooms.
Freezing rain coated trees and lines across much of central and northeastern Oklahoma, bringing a wave of fallen-limb and roof claims.
Very large hail struck parts of the Oklahoma City area, damaging roofs, siding, windows and vehicles in a single afternoon.
One of the most destructive tornadoes in state history, followed eleven days later by the El Reno tornado, the widest on record.
A magnitude 5.8 quake, the strongest recorded in Oklahoma, put earthquake endorsements and masonry cracking in the spotlight.
Ice loaded trees that still had their leaves, snapping limbs onto roofs, fences and vehicles across the metro.
A long stretch of sub-zero temperatures led to burst pipes and interior water losses statewide.
A violent tornado hit Barnsdall and nearby areas north of Tulsa, a reminder that Green Country sees major wind events too.
Each solves a different problem. Picking the right one first saves time and fees — and an Oklahoma Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.
We serve every county in the state. These are the communities where an Oklahoma Insurance Appraiser is called most, each with its own local page.
Straight answers about what appraisal is, what it costs and when it’s the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, build an independent line-item estimate, negotiate with the carrier’s appraiser and, if needed, present the remaining items to a neutral umpire.
No. A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question — the amount of loss. We don’t give legal advice or negotiate outside appraisal.
When coverage is accepted, you have the carrier’s estimate, and your contractor’s number is meaningfully higher — as a rough guide, more than about 10% or several thousand dollars apart.
Generally no. Appraisal sets the amount of loss. Coverage disputes and denials are a different track, often involving an Oklahoma attorney.
Each side usually pays its own appraiser and splits the umpire. We put our fee in writing before any work begins, and the first conversation is free.
Yes. We work in all 77 Oklahoma counties, with frequent work around Oklahoma City, Tulsa, Norman, Lawton, Enid and Stillwater.
Practical guides from Oklahoma Insurance Appraiser on policy wording, documentation and roof-age rules.
A plain guide to the appraisal paragraph in Oklahoma property policies, from the trigger language to the award.
Read the guideWhat to photograph, measure and save after a hailstorm so your claim rests on evidence instead of memory.
Read the guideTwo common endorsements can cut a roof claim before anyone argues about price. Here’s how to spot them and what to do.
Read the guide
A short review now can keep you from accepting a settlement that won’t cover the rebuild.
Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer about whether appraisal is worth pursuing — no pressure, no obligation.